Tucson VA Loan Assumptions: Financing the Gap for Veterans, Non-Veterans & Investors
Think you need the entire cash difference to assume a low-rate VA mortgage? Financing options may help cover that gap. And you don’t have to be a veteran—qualified non-veterans and investors may assume a VA loan, too.
Here’s What That Could Look Like
You find a $400,000 Tucson home with an existing $300,000 VA mortgage at 2.75%.
The difference between the purchase price and mortgage balance is $100,000. That difference is often called the equity gap—the amount you need to pay the seller beyond the mortgage you’re taking over.
You might assume you need all $100,000 in cash.
Not necessarily. If you qualify and financing is available, you may be able to borrow part of that difference while retaining the existing low rate on the assumed mortgage.
Here’s a hypothetical example:
| Purchase details | Amount |
|---|---|
| Home purchase price | $400,000 |
| Existing VA mortgage being assumed | $300,000 |
| Buyer’s cash toward the purchase | $25,000 |
| Second loan covering the remaining gap | $75,000 |
Closing costs, assumption fees and any required reserves would be additional.
Could a VA Loan Assumption Lower Your Monthly Payment?
In this example, the assumed mortgage has 25 years remaining at 2.75%, and the second loan has a hypothetical 8.5% rate over 20 years.
Compare that with a new $375,000 mortgage at a hypothetical 7.30% over 30 years:
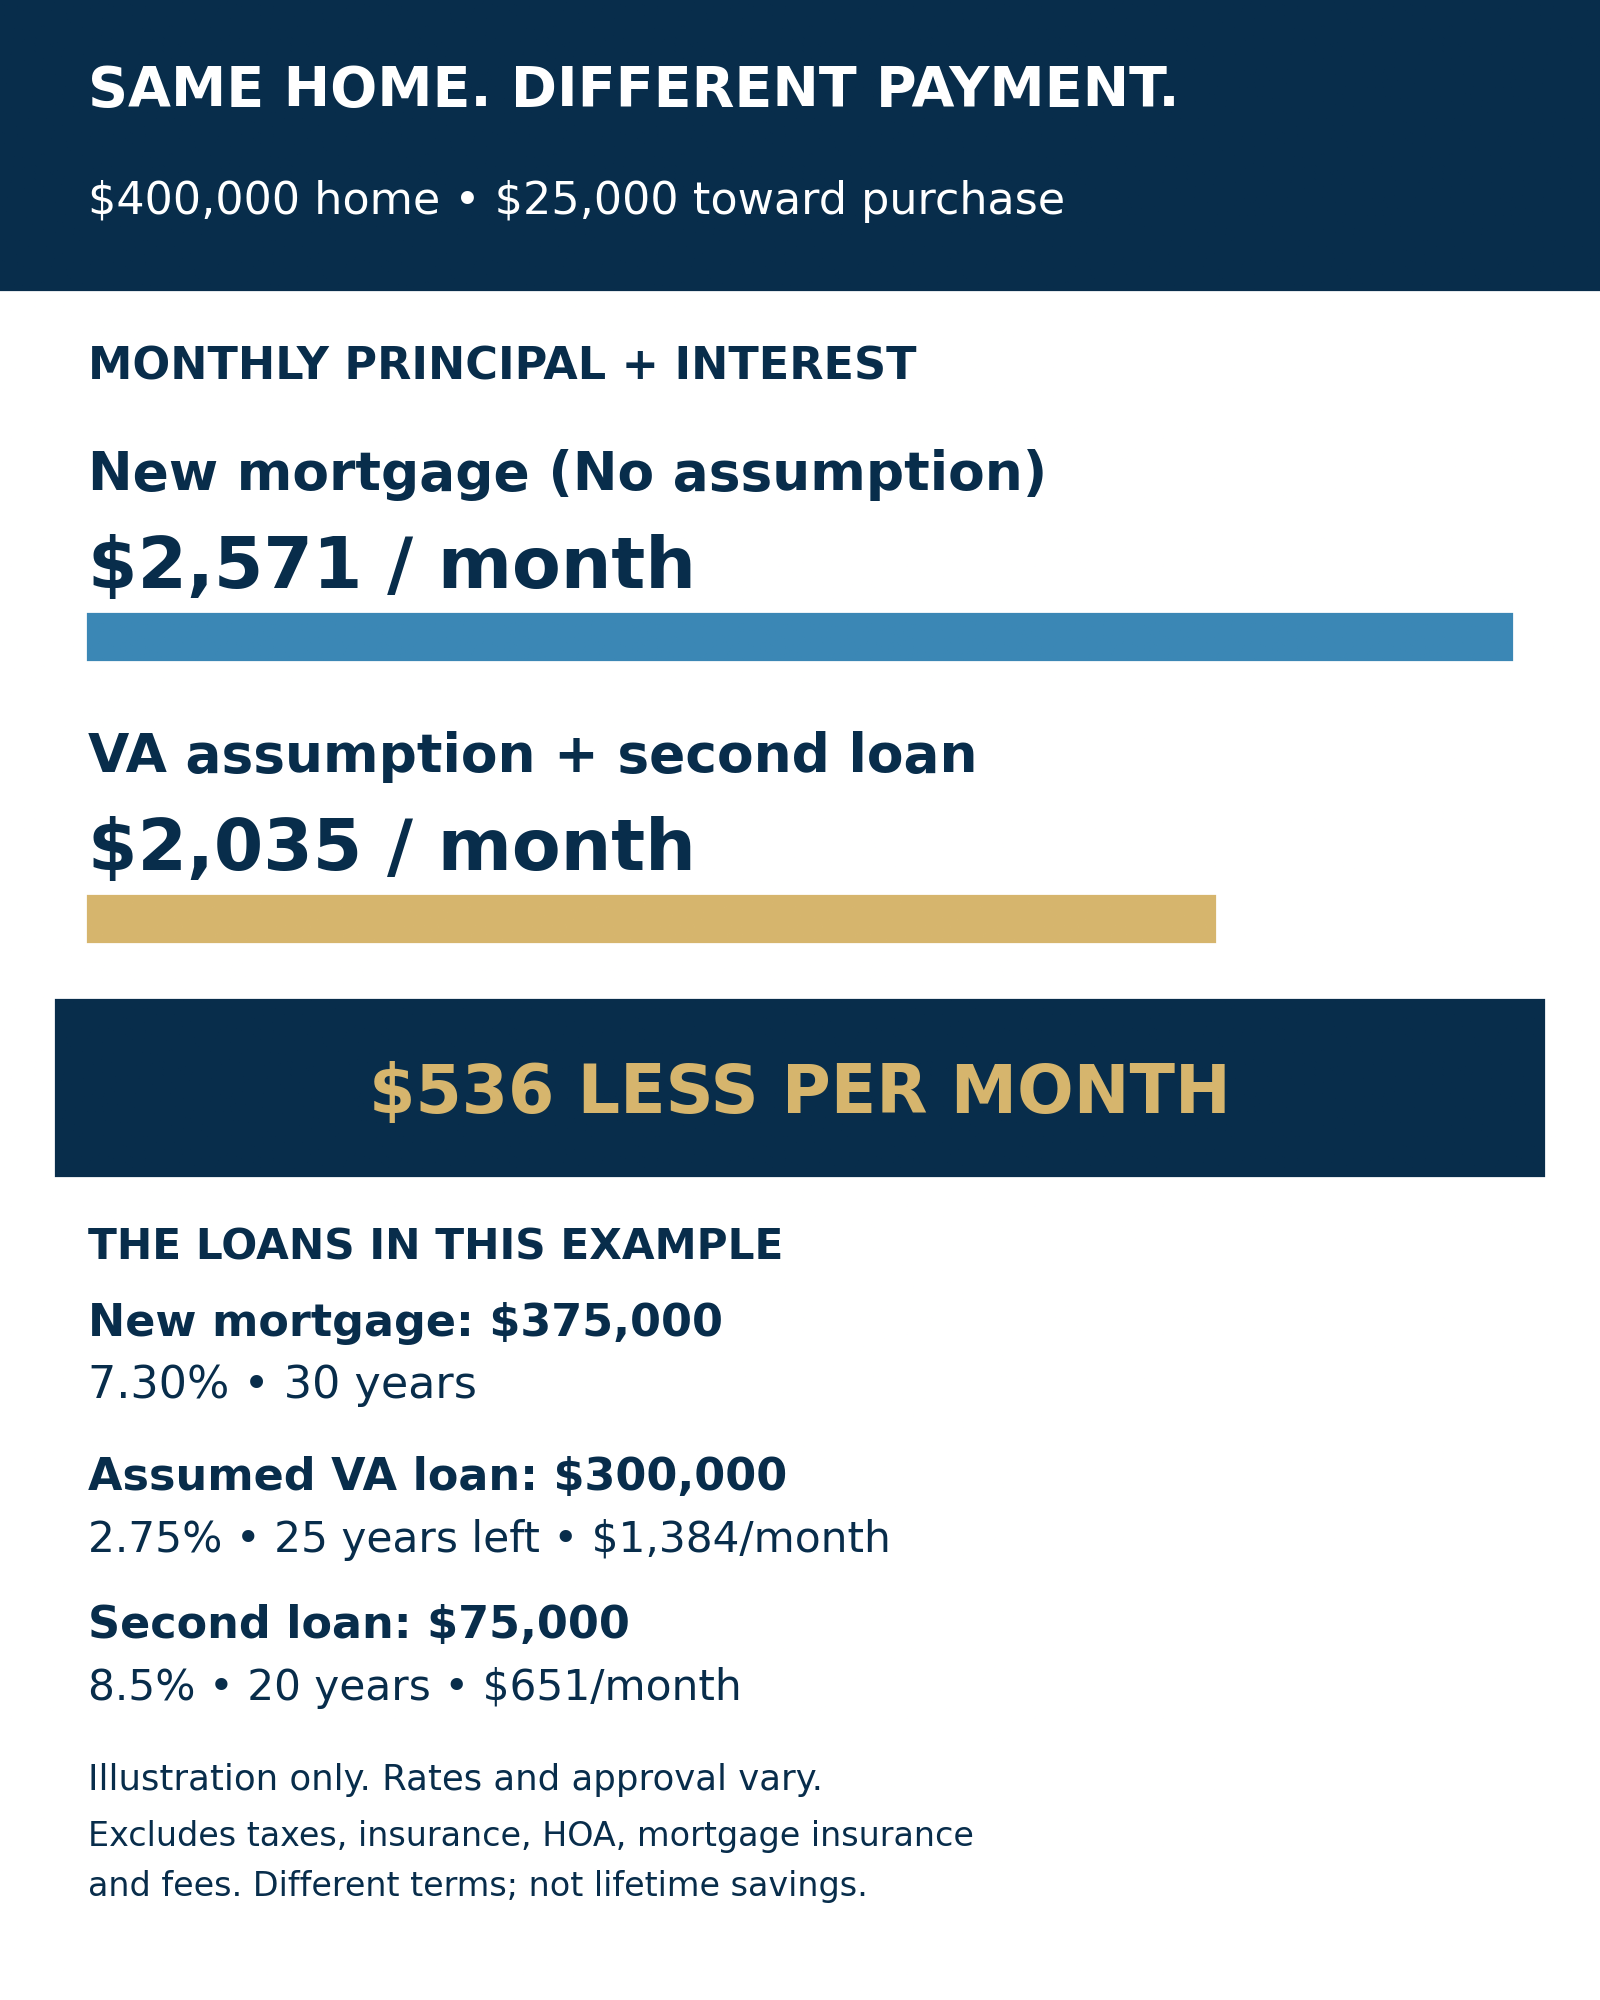
New mortgage without an assumption: approximately $2,571 per month.
VA assumption plus second loan: approximately $2,035 per month combined.
Potential monthly difference: approximately $536.
Both examples involve the same purchase price, buyer contribution and total amount borrowed. The financing structure creates the difference.
These are illustrative principal-and-interest calculations, not loan offers or current rate quotes. Taxes, insurance, HOA dues, mortgage insurance and fees are excluded. The loans have different repayment terms; this is not a comparison of lifetime financing costs.
Can You Finance the Equity Gap on a VA Loan Assumption?
Yes—VA allows secondary financing with an assumption when applicable requirements are met. That does not mean every lender offers it or every buyer will qualify.
The servicer processing the assumption must review the financing arrangement. A second mortgage on the purchased property must remain subordinate to the assumed VA mortgage, and its payment must be included when evaluating the buyer’s debts.
The practical question is: What financing is available for this property, this assumption and your financial situation?
See the VA’s official guidance on secondary financing for loan assumptions.
Can Non-Veterans and Investors Assume a VA Loan?
Yes. A qualified non-veteran can assume an existing VA mortgage without having their own VA home loan eligibility.
Investors and second-home buyers may also qualify for an assumption without substituting VA entitlement. The purchase does not necessarily have to become the buyer’s primary residence.
That is an important difference between assuming an existing VA mortgage and obtaining a new VA purchase loan.
Approval is still required. The buyer must meet applicable credit and income requirements, and the loan’s terms and intended property use need to be reviewed with the servicer.
There is also an important consideration for the seller: without an approved substitution of entitlement, the seller’s VA entitlement generally remains tied to the mortgage until it is paid off. Substituting a veteran buyer’s entitlement involves additional requirements, including occupancy.
The VA’s Assumption Entitlement Acknowledgment explains this distinction.
Create Affordability Through a Strategic Purchase
Affordability is about the purchase price and the financing working together.
An assumption may let you retain a low fixed rate on the existing mortgage balance. Financing part of the equity gap could help preserve cash while still producing a manageable combined payment.
But the complete numbers matter:
-
The purchase price and remaining mortgage balance.
-
The existing interest rate and remaining repayment term.
-
The rate, payment and terms of any additional borrowing.
-
Taxes, insurance, HOA dues, closing costs and maintenance.
-
For investors, realistic rent, vacancy and operating expenses.
A low assumed rate can be an advantage. The opportunity becomes meaningful when the entire purchase works for your budget and goals.
💡 Something to Think About: Using Equity in Your Current Home
Have equity in your primary residence? You may be able to use a home equity line of credit—commonly called a HELOC—to help cover the difference when purchasing another home through a VA loan assumption.
This could provide another source of funds for the equity gap.
The arrangement must meet both lenders’ requirements, and you need to account for the assumed mortgage payment, HELOC payment and existing obligations. HELOC rates are typically variable, and your primary residence secures that additional borrowing.
Serious About Finding a Great Deal? I Want to Help You Get One.
If you’re serious about buying and want to find a great deal, I want to help you get that great deal.
That starts with looking beyond the asking price. An assumable mortgage, negotiated seller assistance or another financing strategy could make a meaningful difference in what you can afford.
We’ll evaluate the property, compare the financing and run the numbers with your lender. My goal is to help you recognize an opportunity—and be ready to act when the right one comes along.
Reach out by phone, text, email or through my website, and I’ll send you active Tucson and Southern Arizona listings advertising assumable financing. We’ll then investigate the loan terms and which opportunities fit your goals.
Explore more Tucson buyer and seller resources.
Billy Morris
REALTOR® | Associate Broker
GRI, MRP | Military Veteran
Realty Executives Arizona Territory
billymorrisrealestate.com
Educational information only. Loan assumptions and additional financing require approval. Availability, rates, terms, costs and eligibility vary. A lower mortgage payment does not guarantee investment cash flow or overall savings.
Categories
Recent Posts